Insurance premium financing is an innovative solution that allows businesses to manage their cash flow more effectively by breaking down the cost of insurance premiums into manageable installments.
If you’ve been considering insurance premium financing, here are some quick benefits:
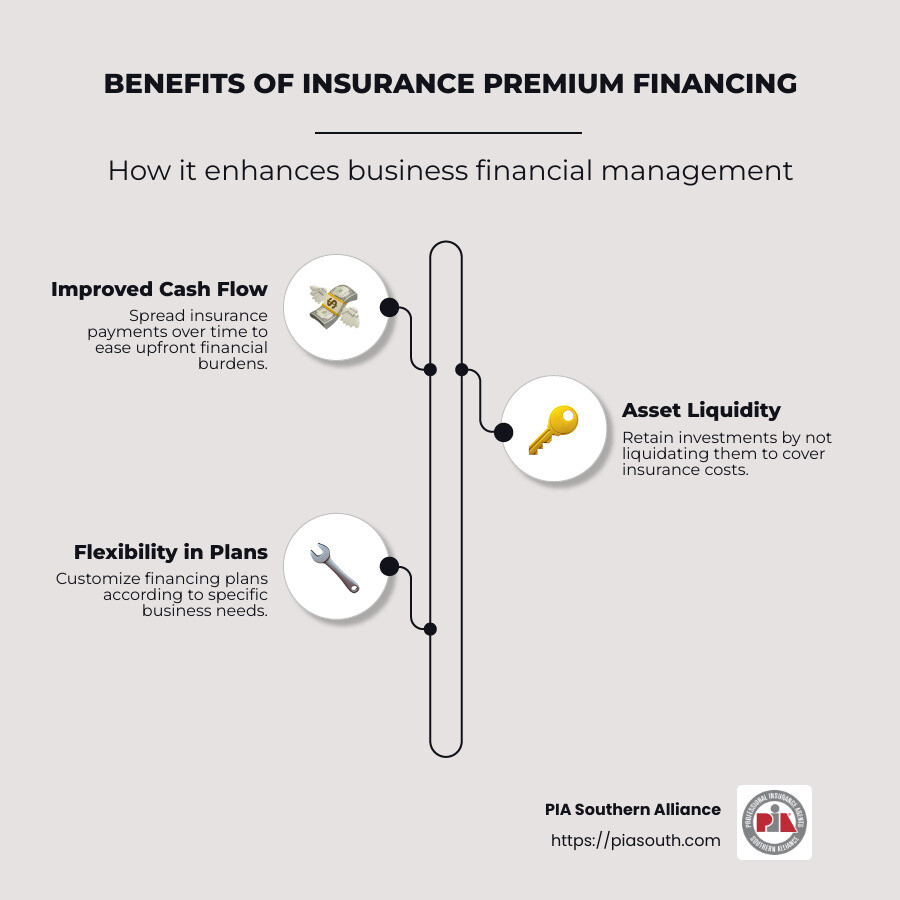
- Improved Cash Flow: Spread payments over time, easing upfront financial burdens.
- Asset Liquidity: Avoid liquidating investments to cover insurance costs.
- Flexibility: Choose customized plans that suit your business needs.
As businesses face complexities in managing finances, insurance premium financing presents a compelling option to ease the pressure without sacrificing essential coverage.
At PIA Southern Alliance, we aim to empower businesses, particularly in the Southeast, to steer the insurance landscape with confidence. Our focus is on enhancing the prosperity of mid-sized independent agents by providing unique education and support in insurance dealings.
Insurance premium financing word roundup:
– can an insurance agency finance a premium
– insurance premium funding interest rates
– insurance premium funding loan
Understanding Insurance Premium Financing
Insurance premium financing is a practical financial tool that helps businesses manage their insurance costs. Instead of paying a hefty insurance premium upfront, businesses can spread these payments over time through a loan arrangement. This setup is particularly beneficial for companies experiencing cash flow challenges.
How It Works
The process of premium financing involves entering into a premium finance agreement. Here’s a simplified breakdown:
Loan Arrangement: A business takes out a loan specifically to cover the cost of their insurance premiums. This loan is typically secured against the cash surrender value of the insurance policy.
Monthly Installments: Instead of a single large payment, the business makes monthly payments to the lender. These installments include both the principal and interest, making it easier to manage cash flow.
Policy as Collateral: The insurance policy itself often acts as collateral for the loan. This means that if the business defaults on the loan, the lender has a claim on the policy.
Benefits
Opting for insurance premium financing offers several advantages:
Cash Flow Control: By spreading out payments, businesses can maintain better control over their cash flow. This is crucial for companies that need to allocate funds to various operational needs without straining their finances.
Asset Liquidity: Businesses can retain their capital and avoid selling off assets to cover insurance costs. This preserves the company’s financial health and flexibility.
Retained Capital: With premium financing, businesses can keep their capital invested in growth opportunities rather than tying it up in insurance payments. This strategic use of funds can lead to better long-term financial outcomes.

In summary, insurance premium financing not only provides financial relief by easing the immediate burden of insurance costs but also supports a business’s broader financial strategy. By working with organizations like PIA Southern Alliance, businesses in Georgia, Alabama, and Mississippi can find custom solutions to meet their specific needs.
Types of Insurance Premium Financing
Insurance premium financing comes in different flavors to suit various needs. Here’s a look at the main types: Traditional Recourse Premium Finance, Non-Recourse, and Hybrid Options.
Traditional Recourse Premium Finance
Traditional recourse premium finance is the classic approach. In this setup, the borrower enters a fully collateralized loan arrangement. This means the loan is backed by assets, often the insurance policy itself or other liquid assets. The goal? To hold the life insurance policy to maturity, which is particularly useful for estate liquidity needs.
This type of financing is ideal for those with a high net worth but who may have assets tied up in non-liquid investments like real estate. By using traditional recourse financing, they can maintain these investments while still covering their insurance costs. The loan terms here are usually favorable, offering advantageous rates and spreads.
Non-Recourse and Hybrid Options
For those who need more flexibility, non-recourse and hybrid premium finance options exist. Unlike traditional recourse loans, non-recourse financing does not require the borrower to personally guarantee the loan. Instead, the lender can only claim the collateral if there’s a default, not the borrower’s other assets. This can be a safer option for those wary of personal financial risk.
Hybrid premium finance blends elements of both recourse and non-recourse options, offering a middle ground. These options often come with specific collateral requirements. For instance, collateral could include cash investments or securities, which need to be verified by a third party annually. This ensures the lender has assurance of the borrower’s ability to meet the loan obligations.
In both non-recourse and hybrid setups, having an investment team manage the collateralized assets can be beneficial. They can ensure that these investments are optimized and aligned with the borrower’s broader financial strategy.
These diverse financing options provide businesses with the flexibility they need to manage their insurance premium costs effectively, ensuring that they can choose a solution that aligns with their financial goals and risk tolerance.
Risks and Mitigation Strategies
Insurance premium financing can be a valuable tool, but like any financial strategy, it comes with its own set of risks. Understanding these risks and how to mitigate them is crucial.
Interest Rate Volatility
Interest rates can be unpredictable. In premium financing, the interest on loans is often tied to an index like LIBOR (London Interbank Offered Rate). If LIBOR rises, so do your interest payments. This means the cost of financing your insurance premiums can increase unexpectedly, potentially impacting your cash flow.
To manage this risk, it’s important to:
- Monitor Interest Rates: Keep an eye on LIBOR trends to anticipate changes.
- Negotiate Fixed Rates: If possible, negotiate a fixed interest rate with your lender to avoid surprises.
- Budget for Fluctuations: Prepare for potential rate increases in your financial planning.
Collateral and Credit Risks
Collateral plays a big role in premium financing. Loans are often collateralized with assets like real estate or securities. But if the value of these assets drops, you might need to provide more collateral.
Here’s how to mitigate these risks:
- Diversify Your Collateral: Use a mix of assets to back your loan. This reduces the impact if one asset loses value.
- Regular Asset Valuations: Conduct regular valuations to ensure your collateral remains sufficient.
- Consult with Experts: Work with financial advisors to manage and optimize your collateralized assets.
Credit rating risk is another consideration. Lenders may reassess terms if the insurance carrier’s credit rating changes. A downgrade can lead to higher borrowing costs or even a call on the loan.
To protect against this:
- Choose Strong Carriers: Opt for insurers with high credit ratings to minimize this risk.
- Stay Informed: Keep track of your carrier’s financial health and industry news.
- Have a Backup Plan: Be ready with alternative financing options if terms change unfavorably.
Understanding these risks and having a plan in place can help you steer the complexities of insurance premium financing and make informed decisions that align with your financial goals.
Insurance Premium Financing for Businesses
Why Businesses Choose Premium Financing
Businesses often face challenges with cash flow. Large insurance premiums can strain financial resources, leaving less room for operational expenses or growth initiatives. Insurance premium financing provides a solution by allowing businesses to pay premiums in installments rather than a lump sum. This helps maintain asset liquidity and ensures that cash is available for other needs.
Consider a trucking company in Georgia. They face high insurance costs due to the nature of their operations. By opting for premium financing, they can spread these costs over several months. This approach keeps their cash flow steady and allows them to invest in fleet expansion or maintenance without financial strain.
Another reason businesses choose premium financing is asset retention. Instead of liquidating assets to cover insurance costs, companies can keep their assets intact. This is particularly beneficial for businesses with valuable equipment or real estate that they prefer not to sell or leverage.
Choosing the Right Program
Selecting the right premium financing program is crucial. Businesses must weigh the loan cost against the benefits of maintaining cash flow and asset retention. Here are some key factors to consider:
Loan Cost: Analyze the interest rates and fees associated with the financing. Ensure that the cost of financing does not outweigh the benefits. For instance, a business in Alabama might find a program with lower interest rates, making it a more viable option.
Exit Strategy: A solid exit strategy is essential. Some financing arrangements allow businesses to pay off the loan directly from the policy’s cash values. This can be an attractive option for companies looking to minimize out-of-pocket expenses.
Flexibility: Look for programs that offer flexible terms. For example, a business in Mississippi may want the option to adjust payment schedules based on seasonal cash flow variations.
Reputation: Work with reputable providers like PIA Southern Alliance, who understand the local market and can offer custom solutions.
By carefully evaluating these factors, businesses can choose a premium financing program that aligns with their financial goals and operational needs. This strategic decision can improve financial stability and support growth initiatives.
Frequently Asked Questions about Insurance Premium Financing
What is insurance premium financing?
Insurance premium financing is a financial arrangement that allows businesses to pay their insurance premiums over time instead of in a single, upfront payment. This is similar to taking out a loan to cover the cost of insurance. The business pays back this loan through monthly installments, which helps manage cash flow and keeps assets liquid.
It’s a popular option for businesses that face high insurance costs but want to maintain financial flexibility. For example, a construction company in Alabama might use premium financing to avoid tying up cash that could be used for other operational needs.
How does premium financing benefit businesses?
Premium financing offers several advantages to businesses:
Cash Flow Management: By spreading premium payments over time, businesses can better manage their cash flow. This is crucial for companies that need to balance multiple financial obligations.
Asset Liquidity: Businesses can keep their assets intact instead of selling or leveraging them to pay for insurance. This is especially important for those with valuable equipment or real estate.
Investment Opportunities: With more cash on hand, businesses can seize new opportunities, such as expanding operations or investing in new technology.
A real-world example: A retail chain in Mississippi uses premium financing to manage insurance costs. This allows them to allocate funds toward opening new store locations, fueling growth without compromising financial stability.
What are the risks involved in premium financing?
While premium financing can be beneficial, it also comes with risks:
Interest Rate Volatility: If interest rates rise, the cost of financing can increase, impacting overall expenses. Businesses need to be prepared for potential fluctuations in rates.
Collateral Requirements: Most financing agreements require collateral. If a business cannot meet these requirements, it may have to use other assets, which could pose a risk if the business faces financial difficulties.
Credit Rating Risk: A business’s credit rating can be affected if it struggles to make payments, potentially impacting its ability to secure future financing.
To mitigate these risks, businesses should work with experienced providers who offer custom solutions and transparent terms. PIA Southern Alliance, for example, offers programs designed to align with a company’s financial strategy and needs, ensuring a balanced approach to premium financing.
Conclusion
PIA Southern Alliance is dedicated to empowering independent insurance agencies in Georgia, Alabama, and Mississippi. We provide the tools and resources necessary to steer the complexities of the insurance landscape, particularly when it comes to insurance premium financing.
Our educational resources are designed to improve strategic decision-making skills. We offer specialized webinars and courses that focus on commercial property insurance, helping agents improve their cross-selling abilities and make informed choices that drive growth.
By leveraging the resources we provide, insurance agents can confidently tackle the challenges of premium financing. Whether it’s understanding the nuances of policy options or effectively managing client relationships, our programs equip agents with the knowledge and skills they need.
In the changing world of insurance, strategic decision-making is key. With PIA Southern Alliance as your partner, you can ensure that your agency not only survives but thrives. Explore our educational programs and let us support you in building a successful agency.