
Can an insurance agency finance a premium? Yes, an insurance agency can indeed finance a premium through premium financing arrangements. This solution provides commercial clients the flexibility to manage their insurance costs more effectively, without needing large upfront payments or liquidating assets. Instead, clients can pay in manageable installments, ensuring their cash flow remains stable.
In today’s evolving insurance market, premium financing has become a game-changer, especially for high-net-worth individuals and businesses with significant insurance needs. These clients often face hefty premiums when securing substantial insurance coverage, whether for property and casualty policies in Georgia, Alabama, or Mississippi or for complex commercial policies. Premium financing helps keep their assets free for investment opportunities, potentially yielding higher returns than the cost of financing the premium.
At PIA Southern Alliance, we believe in empowering independent agencies with resources and solutions they need to offer premium financing. Our aim is to strengthen your agency’s competitive edge and ensure your clients’ diverse needs are met effortlessly.
Understanding Premium Financing
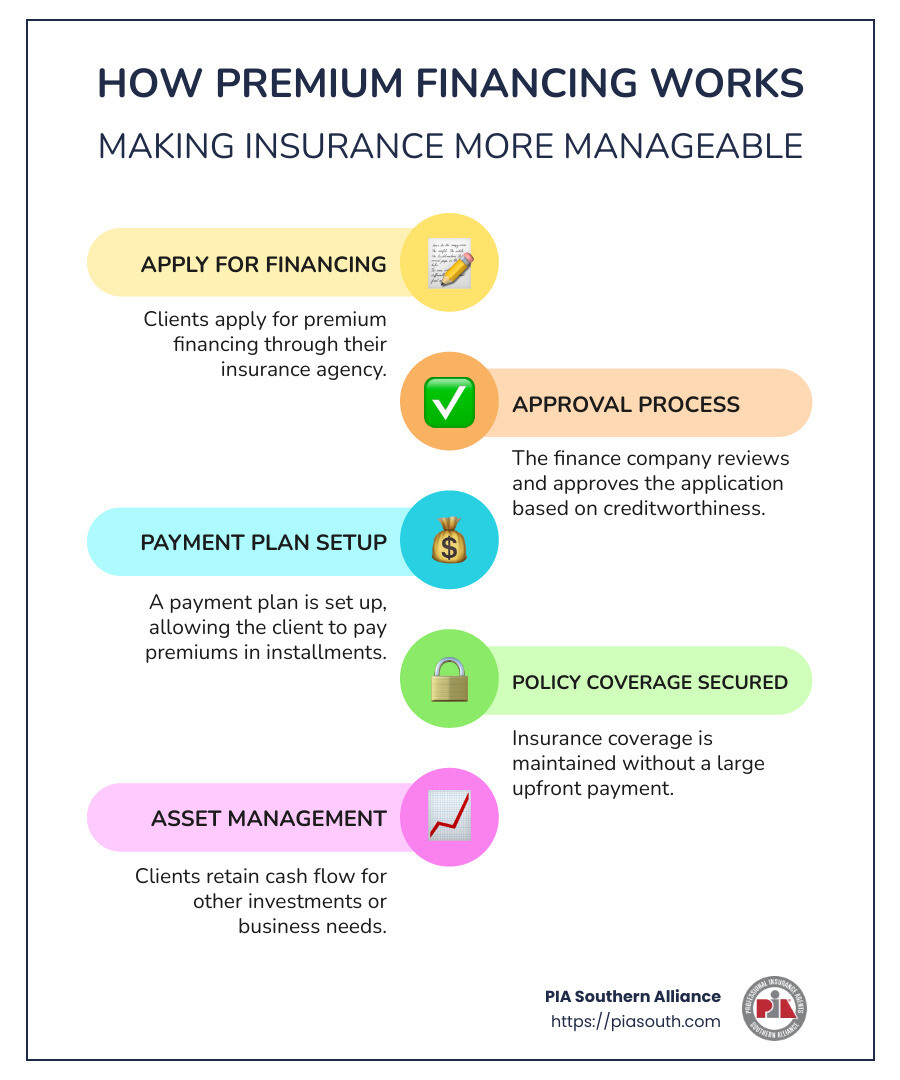
Premium financing is a strategic tool that allows businesses and high-net-worth individuals to manage large insurance premiums without depleting their cash reserves. It involves using a premium finance company to cover the cost of insurance premiums, which the policyholder then repays over time.
How Premium Financing Works
Imagine a commercial client in Georgia needing a substantial property insurance policy to protect their assets. The premium for such a policy can be quite high. Instead of paying it all upfront, the client can work with a premium finance company. This company pays the insurance premium on behalf of the client, who then repays the loan in installments.
This arrangement is particularly beneficial for those with large policies. For instance, businesses that require extensive property and casualty coverage can maintain their liquidity and invest their capital elsewhere, potentially earning more than the interest on the loan.
The Role of Premium Finance Companies
Premium finance companies play a crucial role in this process. They offer the funds needed to cover the insurance premium, allowing clients to spread payments over a period. This not only eases cash flow but also provides a financial cushion, enabling businesses to plan their finances better.
These companies also partner with insurance agencies to offer custom solutions. Agencies can thus provide their clients with flexible payment options, enhancing their service offerings and client satisfaction.
Commercial Insurance and Premium Financing
For commercial clients, premium financing is particularly advantageous. It offers a way to manage the substantial costs associated with commercial insurance policies. Whether it’s a business in Alabama needing comprehensive liability coverage or a corporation in Mississippi looking for robust property protection, premium financing can make these policies more accessible.
Premium financing allows businesses to maintain their operational cash flow while ensuring they have the necessary insurance coverage to protect their assets. This financial strategy not only supports growth but also provides peace of mind.
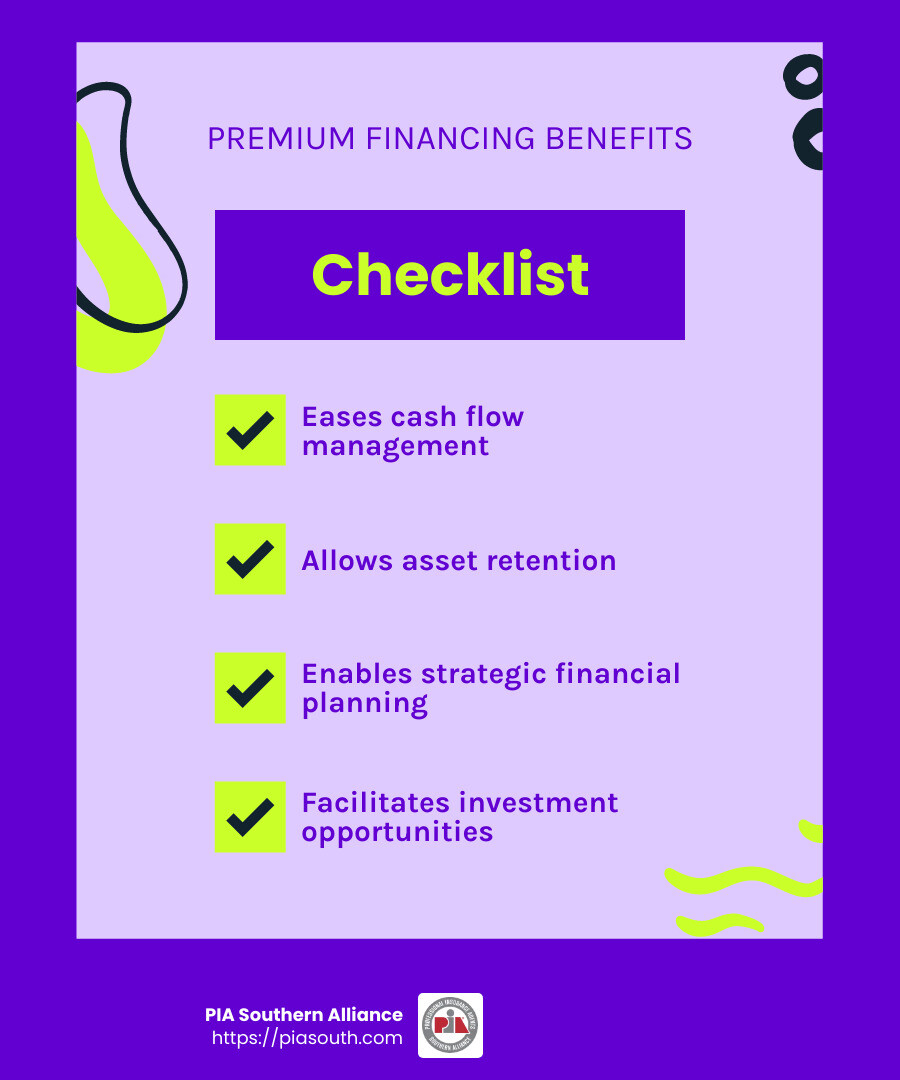
By leveraging the expertise of premium finance companies, agencies can offer clients a valuable service that aligns with their financial goals. This approach not only benefits clients but also positions the agency as a trusted advisor in the complex insurance landscape.
Can an Insurance Agency Finance a Premium?
How Agencies Facilitate Premium Financing
Yes, an insurance agency can indeed finance a premium, and they often do so through various methods that improve both their service offerings and profitability. Let’s explore how this works.
Agency-Owned Finance Companies
Some insurance agencies decide to create their own premium finance companies. This approach allows them to directly manage the financing of premiums, turning it into a profit center. By doing so, agencies can control the financing process, set competitive rates, and offer customized payment plans to their clients. This not only increases their revenue but also strengthens client relationships by providing custom financial solutions.
Third-Party Finance and Agency Partnerships
For agencies that prefer not to manage a financing company, partnering with third-party premium finance companies is a viable option. These partnerships allow agencies to offer premium financing without the need to handle the administrative and financial complexities themselves. The third-party company handles the logistics, while the agency benefits from offering an additional service to its clients.
Premium Finance Platforms
Many agencies leverage premium finance platforms. These platforms simplify the process by providing real-time quoting and flexible payment options. They enable agencies to quickly offer financing solutions, improving client satisfaction and operational efficiency.
For example, a property and casualty insurance agency in Georgia might use such a platform to help a commercial client finance a large liability policy. The client benefits from manageable payments, while the agency improves its service portfolio.
The Strategic Advantage
By offering premium financing, agencies in states like Alabama and Mississippi can attract more clients and increase retention. It allows them to compete more effectively by providing comprehensive financial solutions that meet diverse client needs.
In summary, whether through agency-owned finance companies, third-party partnerships, or digital platforms, agencies have several avenues to finance insurance premiums. This flexibility not only supports cash flow management for clients but also positions the agency as a key player in the insurance market.
Benefits of Financing Your Insurance Premium
Financing your insurance premium can offer several compelling benefits. Let’s explore the key advantages, including cash flow management, asset retention, and investment opportunities.
Cash Flow Management
One of the primary benefits of financing your insurance premium is improved cash flow management. Instead of making a large upfront payment, policyholders can spread the cost over time. This approach frees up cash that can be used for other expenses or investments, providing greater financial flexibility.
For instance, a business in Mississippi might choose to finance a substantial commercial property policy. By doing so, they can maintain their liquidity and allocate funds to other critical areas, such as expanding their operations or managing day-to-day expenses.
Asset Retention
Another significant advantage is asset retention. Financing allows policyholders to keep their assets invested rather than liquidating them to cover insurance costs. This is particularly beneficial for high-net-worth individuals and businesses with significant investments.
Consider a commercial client in Alabama who wants to retain their investment portfolio while still securing necessary insurance coverage. By opting for premium financing, they can keep their investments intact, potentially earning returns while paying for their insurance over time.
Investment Opportunities
Financing premiums can also open up new investment opportunities. With more cash on hand, policyholders can pursue ventures that may yield higher returns than the cost of financing. This strategic use of funds can improve overall financial growth and stability.
For example, a property and casualty insurance client in Georgia might use the funds saved from premium financing to invest in a new business project or real estate opportunity. The potential gains from these investments could outweigh the interest costs associated with the financing arrangement.
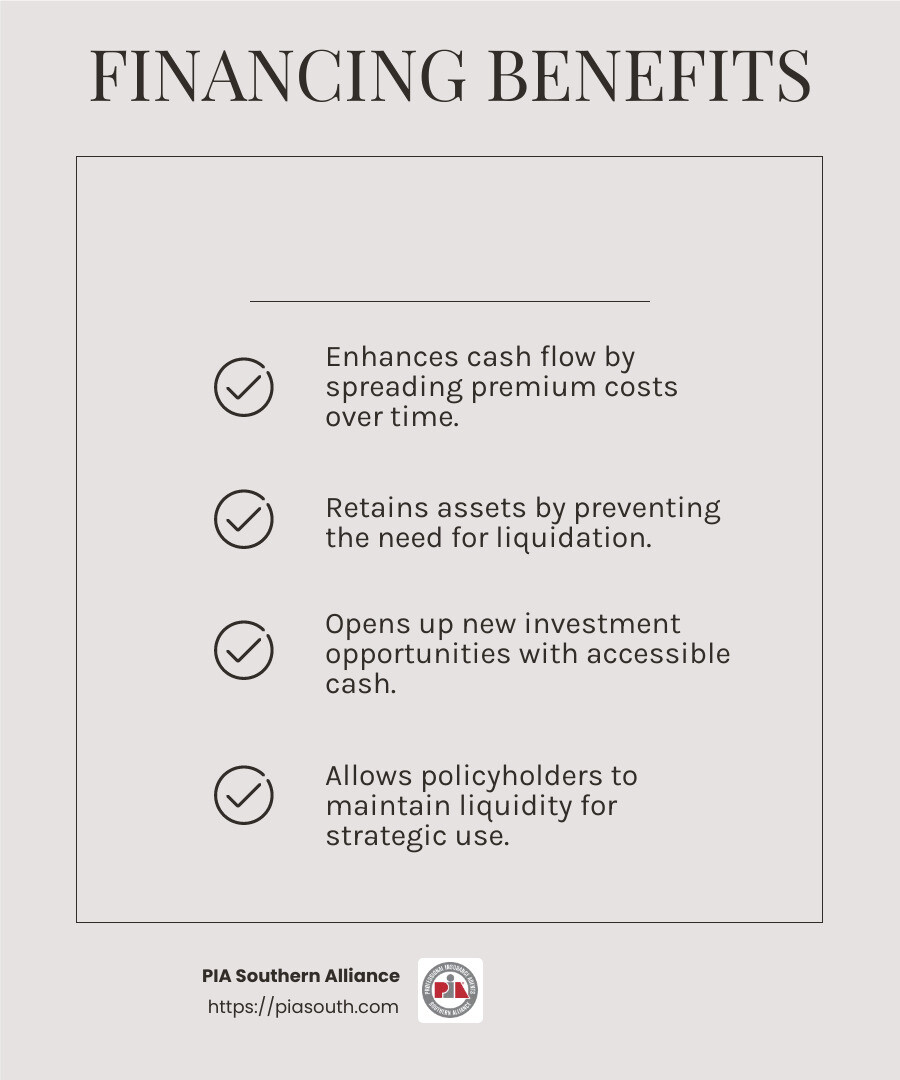
In summary, financing your insurance premium can be a smart financial move. It helps manage cash flow, retain assets, and seize investment opportunities, making it an attractive option for both individuals and businesses.
Next, we’ll explore the potential risks and considerations involved in premium financing to ensure you make an informed decision.
Risks and Considerations
While financing your insurance premium can offer many benefits, it’s crucial to understand the potential risks and considerations. Let’s break down some key factors: interest rates, credit ratings, and lender risks.
Interest Rates
Interest rates can be a double-edged sword. They might start low, making financing appealing. But remember, rates can change over time. If they rise, the cost of your financing can increase significantly.
Imagine you’re a business owner in Georgia financing a major property insurance policy. If interest rates climb, your monthly payments could become much higher than expected, affecting your overall budget.
Credit Ratings
The credit rating of your insurer is another important consideration. If an insurance company’s credit rating drops, it could impact your financing arrangement. A premium finance company might decide not to continue the policy or demand changes to the terms.
For instance, a commercial client in Alabama could face challenges if their insurer’s credit rating falls. This might lead to a scramble for new financing options or even a shift to a different insurer.
Lender Risks
Lender stability is also a critical factor. What happens if your premium finance company faces financial difficulties or goes out of business? This scenario can disrupt your financing plan and leave you searching for alternatives.
Consider a high-net-worth individual in Mississippi using a premium finance company to manage their insurance costs. If that company suddenly shuts down, the individual might need to quickly find a new lender or risk losing their coverage.
Understanding these risks is essential for making informed decisions about premium financing. Being aware of interest rate fluctuations, credit ratings, and lender stability can help you steer potential pitfalls and maintain financial stability.
Next, we’ll address some frequently asked questions about premium financing to further clarify this complex topic.
Frequently Asked Questions about Premium Financing
Can an Insurance Agency Finance a Premium?
Yes, an insurance agency can indeed finance a premium. This is often done through agency-owned finance companies or partnerships with third-party premium finance companies. These arrangements allow agencies to offer their clients the option to spread out the cost of their insurance premiums over time, rather than paying a large sum upfront. This can turn the agency into a profit center, as it can earn revenue through competitive revenue-sharing opportunities with finance partners.
What Are the Benefits of Premium Financing?
Premium financing offers several advantages. One of the primary benefits is improved cash flow management. By financing premiums, clients can retain their cash for other investments or expenses, rather than tying up large amounts of money in insurance payments.
For example, a business in Georgia might use premium financing to maintain liquidity, allowing them to invest in growth opportunities while still having the necessary insurance coverage.
Another benefit is asset retention. High-net-worth individuals and commercial clients often have significant assets that they prefer not to liquidate. Premium financing allows them to keep these assets intact while still obtaining the insurance coverage they need. This strategy can be particularly attractive when the potential return on investments is higher than the interest on the financed premiums.
Who Should Consider Premium Financing?
High-net-worth individuals and commercial clients are prime candidates for premium financing. These groups typically have larger insurance needs, which can result in substantial premium costs. For instance, a commercial client with extensive property holdings in Alabama might find premium financing beneficial to manage their insurance costs without disrupting their operational cash flow.
Similarly, high-net-worth individuals in Mississippi might use premium financing to cover significant life insurance policies, ensuring they don’t have to liquidate valuable assets or incur capital gains taxes.
Premium financing can be an effective strategy for those who want to maintain financial flexibility and optimize their asset management. However, evaluate the risks and benefits carefully to determine if it’s the right choice for your specific situation.
Next, we’ll explore more about how agencies can facilitate premium financing and the platforms they use.
Conclusion
At PIA Southern Alliance, we are committed to empowering independent insurance agencies in Georgia, Alabama, and Mississippi. Our focus is on providing the educational resources and strategic support necessary to steer complex insurance landscapes effectively.
Premium financing is a powerful tool that can help agencies improve their service offerings and improve their bottom lines. By understanding how to leverage agency-owned finance companies or partnerships with third-party finance firms, agencies can transform into profit centers. This not only benefits the agency but also offers clients flexible payment options that support their financial goals.
Our specialized webinars and courses are designed to improve strategic decision-making skills, particularly in commercial property insurance. We help agents hone their cross-selling abilities, allowing them to offer comprehensive solutions that meet the diverse needs of their clients.
If you’re ready to take your agency to the next level, explore our Professional Agents Funding page to learn more about how premium financing can work for you. Let PIA Southern Alliance be your partner in building a successful and sustainable insurance agency.